Choosing the right payment gateway is one of the most consequential decisions a Nigerian SME makes. The wrong choice means failed transactions, slow settlements, manual reconciliation headaches, and customers who abandon payment before completing an order. The right choice means smooth collections, fast payouts, and financial visibility that grows with the business.
But here is what most payment gateway comparison guides do not tell you: most Nigerian SMEs outgrow a basic payment gateway faster than they expect. Collecting payments is only the beginning. As the business grows, the real challenge becomes managing the entire payment cycle: collections, vendor payments, expense approvals, FX transactions, and reconciliation, across a growing number of transactions, channels, and team members.
That is why the most important question is not just which payment gateway collects money the fastest. It is which payment infrastructure gives your business the visibility and control to manage money at scale.
Duplo is built for exactly that. It combines payment collections, virtual accounts, payouts, FX support, expense management, and auto-reconciliation in one connected platform, giving Nigerian SMEs the financial operations infrastructure they need from day one.
This guide covers the seven best payment options in Nigeria for SMEs in 2026, starting with the most comprehensive solution available.
What is a Payment Gateway?
A payment gateway is the digital infrastructure that enables businesses to accept and process payments from customers. Think of it as the bridge between your customers’ payment methods (cards, bank accounts, mobile money) and your business bank account.
When a customer clicks “Pay Now” on your website or app, the payment gateway handles the complex process of:
- Securely capturing payment information
- Encrypting sensitive data
- Communicating with banks and card networks
- Authorizing the transaction
- Transferring funds to your account
For Nigerian SMEs, a good payment gateway must handle the realities of the local market: supporting USSD and bank transfers alongside cards, processing reliably, and settling funds quickly to protect cash flow. But as transaction volumes grow and financial operations become more complex, a standalone payment gateway becomes one of many disconnected tools.
The businesses that scale most efficiently are those that move from a basic payment gateway to a connected financial operations platform before the fragmentation becomes a problem.
Critical Factors When Choosing Payment Gateways in Nigeria
Transaction fee structure. Nigerian payment gateways typically charge 1.4% to 3.9% per transaction. On NGN 1 million monthly volume, the difference between 1.5% and 3.9% is NGN 24,000 per month and NGN 288,000 per year. Understand both percentage rates and flat fees before committing.
Settlement speed. Settlement times range from same-day to T+5. For cash-flow-dependent SMEs, faster settlement is worth evaluating carefully.
Payment method coverage. Nigerian customers use Verve, Visa, Mastercard, bank transfers, USSD, and mobile money. Missing a popular method means losing customers who cannot pay their preferred way.
Reconciliation capability. Manual reconciliation of high-volume bank transfers is one of the largest drains on finance team time in Nigerian SMEs. Virtual accounts that automatically match transfers to the correct invoice eliminate this problem at the source.
Platform depth. A payment gateway that only handles collections forces growing businesses to add separate tools for vendor payments, expense management, and FX. A connected platform handles all of these from one system.
The 7 Best Payment Gateways for Nigerian SMEs
1. Duplo
Best for: Innovative SMEs and enterprise businesses seeking a payment gateway with built-in reconciliation, payouts, and end-to-end financial operations.
Pricing:
- Bank transfers: 1.15% + ₦50 per transaction, capped at ₦1,500
- Local cards: 1.5% + ₦100 per transaction, capped at ₦2,000
- International cards: 4.8%
- Custom volume tiers available for high-volume processing
Why businesses choose Duplo
Duplo gives Nigerian businesses a way to accept payments, track incoming funds, and reconcile transactions without building their financial processes around disconnected tools. Its payment gateway supports Visa and Mastercard transactions from over 160+ countries, alongside local collection options such as bank transfers, OPay, and USSD. Businesses can also generate payment links for customers who need a simple way to pay without a custom checkout integration.
For businesses handling frequent bank transfers, Duplo’s virtual accounts can automatically match incoming payments to the appropriate invoices, reducing the manual work involved in identifying transactions. On the payout side, Duplo supports instant NGN payouts through NIP, alongside international payments in USD and GBP.
More than a payment gateway
What sets Duplo apart is that businesses can connect payment collection with the financial operations that follow. Beyond accepting customer payments, Duplo helps businesses manage payouts, control expenses, automate workflows, and gain better visibility into their finances.
- Automated reconciliation: Match incoming payments to invoices and transaction records, reducing manual tracking and reconciliation work.
- Vendor and supplier payments: Make local and international business payments and manage bulk payouts to up to 500 recipients in a single run.
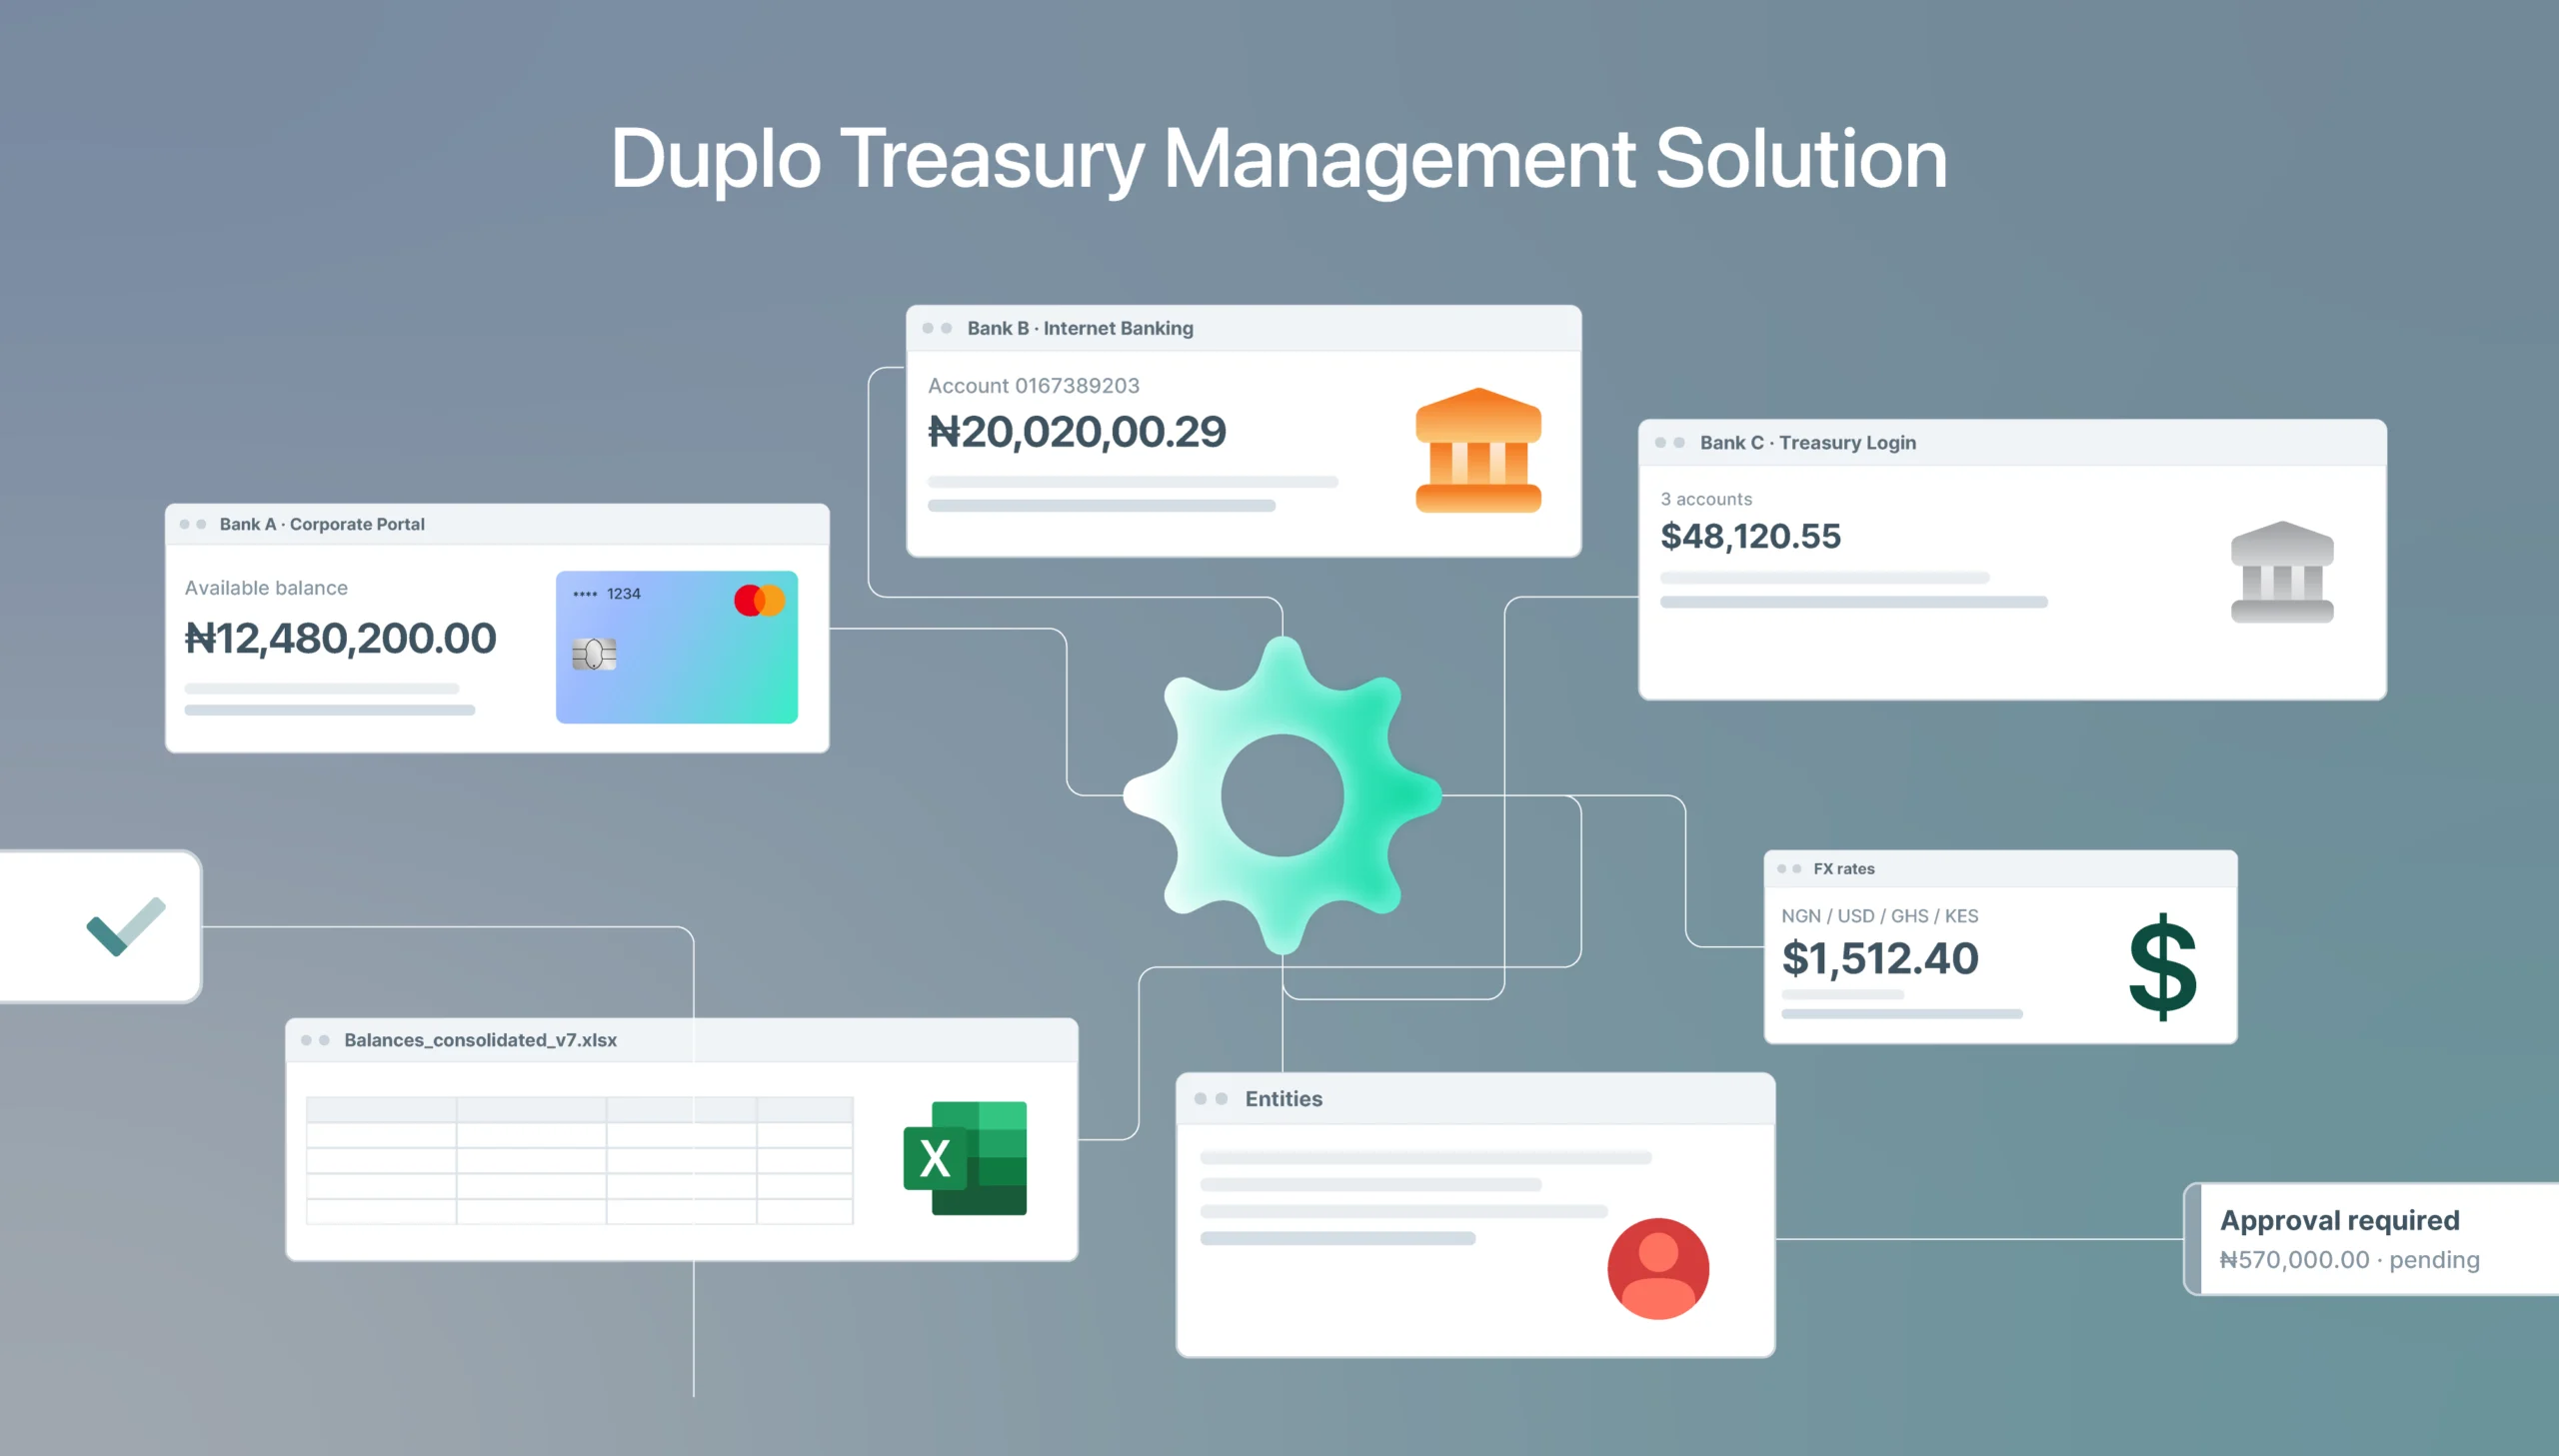
- Treasury Management System (TMS): Gain better visibility into cash positions and treasury activity to support liquidity management and more informed financial decisions.
- Expense management and approvals: Manage business expenses, route requests through structured approval workflows, and establish spending controls.
- FX and international payments: Manage supported international transactions and foreign exchange needs through the platform.
- Accounting integrations: Connect financial workflows with QuickBooks, Sage, and Xero to reduce duplicate data entry and improve financial visibility.
- NRS e-invoicing: Access NRS-compliant e-invoicing capabilities within the platform.
Security and compliance
Duplo’s payment infrastructure is supported by its stated regulatory licences and compliance credentials, including CBN licensing, NRS Systems Integrator and Access Point Provider licences, PCI DSS certification, ISO certification, and NDPC registration.
2. Paystack
Best for: Tech-savvy SMEs prioritising developer experience and modern API features.
Pricing: 1.5% + ₦100 local, 3.9% + ₦100 international.
Paystack offers strong API documentation, fast onboarding, and support for cards, bank transfers, USSD, and mobile money. It is a capable standalone payment gateway for digital-first businesses collecting from Nigerian customers. Settlement is T+1. The ₦100 flat fee component disproportionately impacts smaller transactions.
3. Flutterwave
Best for: SMEs planning multi-country expansion or with international customer bases.
Pricing: 1.4% local + 0.6% platform fee, 4.8% international.
Flutterwave covers 34+ African countries and supports 150+ currencies. Payment links and invoice features require no code. Settlement is T+1. Support response times can vary during high-volume periods.
4. Interswitch Payment Gateway
Best for: Established SMEs prioritising Nigerian market depth and traditional banking relationships.
Pricing: 1.5% for local transactions (capped at ₦2,000) and 5% for international transactions, except AMEX at 4.5%.
Interswitch has deep Nigerian market penetration and strong Verve card processing across 70+ million cardholders. It is a reliable choice for Nigeria-focused businesses with established banking relationships.
5. Remita
Best for: SMEs dealing with government contracts, corporate clients, or requiring broad collection channels.
Pricing: 2% capped at ₦2,500. Foreign cards attract an additional 2% charge. Minimum fee ₦100.
Remita supports internet banking, cards, bank branches, USSD, and agents, making it the broadest channel coverage of any option on this list. Its government payment integration makes it particularly valuable for B2B and B2G businesses. Higher percentage fees compared to competitors are offset by the fee cap on large transactions.
6. Monnify by Moniepoint
Best for: SMEs needing virtual accounts for automated reconciliation and high transaction volumes.
Pricing: Competitive rates in the 1.4% to 1.5% range. Virtual account features included.
Monnify’s virtual account capability simplifies reconciliation for businesses handling high transaction volumes, automatically matching incoming transfers to the correct record without manual investigation. Fast settlement and strong API documentation. Backed by Moniepoint’s infrastructure.
7. OPay Checkout
Best for: SMEs targeting OPay’s mobile wallet user base and prioritising instant settlement.
Pricing: 1.5% local capped at ₦2,000. 4.0% international. No setup fees.
OPay’s direct wallet integration gives businesses access to a large active mobile payments user base with instant settlement to OPay Business accounts. The competitive local fee structure keeps costs low. International reach is more limited than Flutterwave and enterprise features are less developed than established market leaders.
How the 7 Options Compare
| Provider | Local Fee | Settlement | Virtual Accounts | Vendor Payments | Expense Management | Auto Reconciliation |
| Duplo | 1.5% cap ₦2,000 | Instant | ✓ | ✓ | ✓ | ✓ |
| Paystack | 1.5% + ₦100 | T+1 | Limited | ✗ | ✗ | ✗ |
| Flutterwave | 1.4% + 0.6% | T+1 | Limited | ✗ | ✗ | ✗ |
| Interswitch | 1.5% cap 2,000 | Varies | ✗ | ✗ | ✗ | ✗ |
| Remita | 2% cap ₦2,500 | Varies | ✗ | ✗ | ✗ | ✗ |
| Monnify | 1.4–1.5% | Fast | ✓ | ✗ | ✗ | Limited |
| OPay | 1.5% cap ₦2,000 | Instant | ✗ | ✗ | ✗ | ✗ |
Making Your Decision: A Practical Framework
With multiple solid payment gateway options in Nigeria, use this framework to decide:
If you are just starting and need the fastest setup: Paystack or Flutterwave offer straightforward onboarding and broad payment method support for businesses beginning to accept digital payments.
If you serve government or corporate clients: Remita’s broad channel support and institutional payment relationships add specific value for B2B and B2G businesses.
If you process high volumes and need automatic reconciliation: Monnify’s virtual accounts reduce manual finance work significantly for businesses managing large numbers of incoming transfers.
If you are building for scale and need more than collections: Duplo is the only option on this list that handles the full payment lifecycle. Collections, vendor payments, expense management, FX, auto reconciliation, and NRS-compliant invoicing in one connected platform. Nigerian SMEs that choose Duplo are not just choosing a payment gateway. They are choosing the financial operating infrastructure that removes the need to add separate tools as the business grows.
Beyond the Payment Gateway: Building Complete Payment Infrastructure
Payment gateways handle collections, but Nigerian SMEs need a comprehensive financial infrastructure:
Expense Management: Tools for tracking and approving business expenses as operations grow.
Vendor Payments: Systems for paying suppliers efficiently, especially when scaling.
Multi-Currency Support: Capabilities for handling international payments as businesses expand.
Financial Reporting: Integrated reporting for understanding cash flow and financial health.
While specialized payment gateways in Nigeria excel at collecting customer payments, platforms like Duplo provide comprehensive financial operations infrastructure, combining payment processing with expense management, vendor payments, and financial visibility that growing SMEs require.
Conclusion: Choose a Payment Platform That Can Scale With Your Business
Choosing a payment gateway is no longer just about collecting payments. As businesses grow, they also need better visibility into transactions, faster reconciliation, expense controls, payouts, reporting, and operational efficiency.
That’s why businesses are increasingly looking beyond standalone payment gateways and adopting more connected financial infrastructure.
Duplo combines payment collections, payouts, virtual accounts, FX support, reconciliation, expense management, and financial workflows in one platform, helping businesses manage not just how they collect money, but how money moves across the entire business.
Whether you’re processing local card payments, managing vendor payouts, tracking business expenses, or reconciling transactions across teams, Duplo gives finance and operations teams the visibility and control they need to scale more efficiently.
Instead of stitching together multiple disconnected tools as your business grows, you can manage your financial operations from one integrated platform.
👉 Need comprehensive financial infrastructure beyond just payment collection? Explore how Duplo helps Nigerian SMEs manage payments, expenses, and financial operations through a single integrated platform.
Frequently Asked Questions
What is the best payment gateway in Nigeria for SMEs in 2026?
The best payment gateway depends on your specific needs. For businesses that need only to collect payments from customers, Paystack and Flutterwave offer strong developer experience and broad payment method coverage. For businesses that need collections, vendor payments, expense management, FX support, and auto reconciliation in one connected platform, Duplo is the most comprehensive option available for Nigerian SMEs in 2026.
How much do payment gateways charge in Nigeria?
Nigerian payment gateways typically charge between 1.4% and 3.9% per transaction for local cards, with additional flat fees ranging from ₦100 to ₦2,000 depending on the provider. International card transactions typically attract fees of 3.8% to 4.8%. Duplo charges 1.5% capped at ₦1,200 to ₦1,300 for local cards and 3.8% to 4.0% for international cards, with custom volume tiers available for high-volume processing.
What is the difference between a payment gateway and a payment platform?
A payment gateway handles the collection of payments from customers. A payment platform covers the full payment lifecycle: collecting money in, paying vendors and suppliers out, managing foreign currencies, approving spend, and reconciling every transaction automatically. Duplo is a payment platform that includes gateway capability rather than a standalone gateway, making it the more complete solution for growing Nigerian businesses.
How do virtual accounts help Nigerian SMEs with reconciliation?
Virtual accounts assign a unique account number to each customer or invoice. When a customer makes a bank transfer to that account number, the payment is automatically matched to the correct record without manual investigation. Duplo’s virtual accounts eliminate the unmatched transfer problem that currently consumes significant finance team time at most Nigerian businesses managing high-volume bank transfer collections.
Does Duplo support international card payments for Nigerian businesses?
Yes. Duplo accepts international Visa and Mastercard payments from customers in 200+ countries. International card transactions settle in naira into the business’s Duplo account. Duplo also supports FX payments in USD and GBP for Nigerian businesses paying overseas vendors and suppliers.